Free editorial reuse with the Tax Watch branding, reporting period, source and caveats intact. No implied endorsement. Original source documents remain subject to their publishers’ terms.
Featured order follows publication of changed evidence or design—not a daily rotation. All previous editions stay available below. SVGs are static; embeds use one brief, reduced-motion-aware entrance effect.
AUDITED GENERAL FUND · FY2025Fiscal year ended August 31, 2025
Evidence pack includes chart rows, PDF pages, source URL/hash, methodology, summaries and edition ID; it does not bundle the source PDF.
Embed this graphic
This edition remains unchanged, even after newer records arrive. Check revision notes before reuse. Embeds contain no analytics scripts or cookies. Hosting still receives ordinary web requests.
Responsive width; adjust the iframe height for your layout. The data table remains scrollable inside the frame.
Reporting brief, source and accessible table
Short factual summary
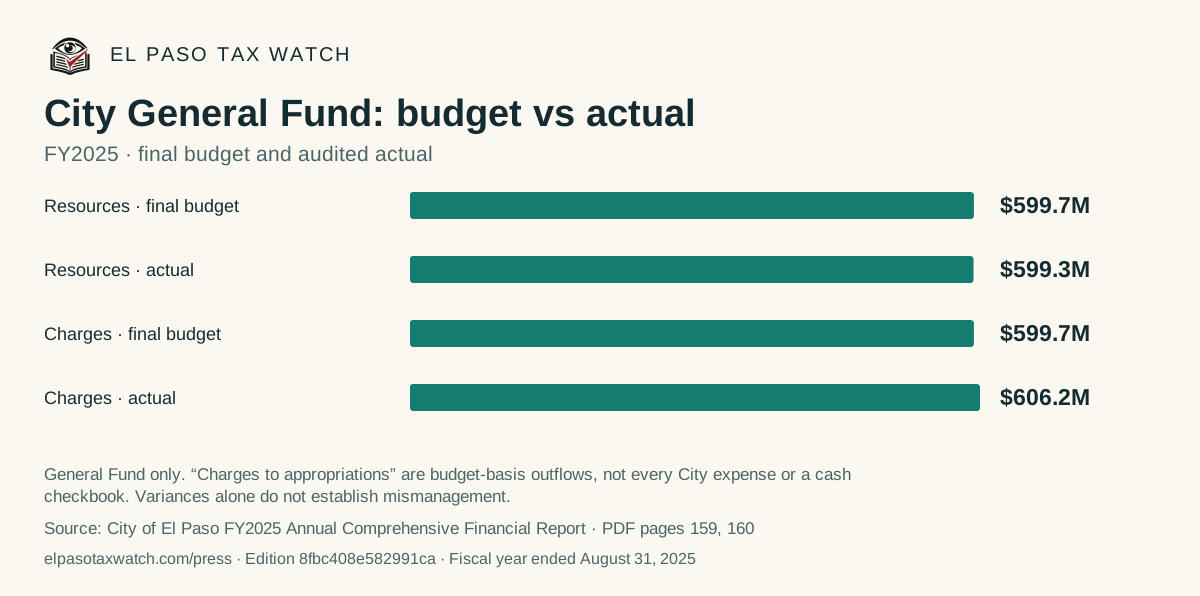
For FY2025, audited General Fund current-year resources were $394,907 below the final budget, while charges to appropriations were $6,481,612 above final appropriations. The schedule reports an ending fund balance of $161,616,210.
Resumen: En el año fiscal 2025, los recursos auditados del Fondo General fueron $394,907 menores que el presupuesto final, mientras que los cargos a las asignaciones superaron las asignaciones finales por $6,481,612. El saldo final del fondo fue $161,616,210.
Question to pursue: Which departments and budget amendments explain the difference, and how much was planned use of fund balance?
Limit: General Fund only. “Charges to appropriations” are budget-basis outflows, not every City expense or a cash checkbook. Variances alone do not establish mismanagement.
Evidence pack includes chart rows, PDF pages, source URL/hash, methodology, summaries and edition ID; it does not bundle the source PDF.
Embed this graphic
This edition remains unchanged, even after newer records arrive. Check revision notes before reuse. Embeds contain no analytics scripts or cookies. Hosting still receives ordinary web requests.
Responsive width; adjust the iframe height for your layout. The data table remains scrollable inside the frame.
Reporting brief, source and accessible table
Short factual summary
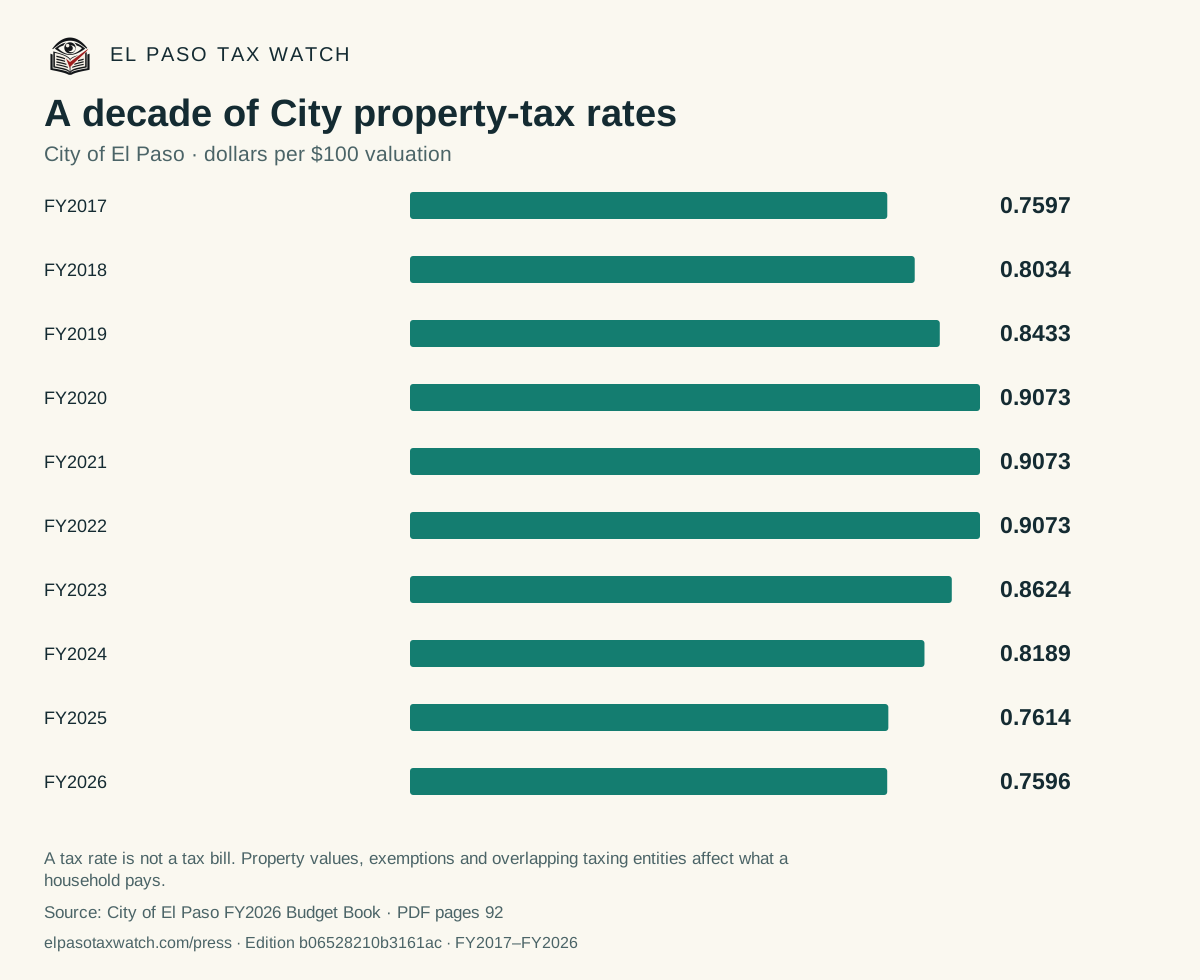
The City of El Paso budget book shows the published property-tax rate rising through FY2020, remaining at that level through FY2022, and then declining through FY2026. A lower rate does not necessarily mean a lower tax bill.
Resumen: El libro presupuestario de la Ciudad muestra que la tasa publicada subió hasta el año fiscal 2020, se mantuvo hasta 2022 y luego bajó hasta 2026. Una tasa menor no necesariamente significa una factura menor.
Question to pursue: How did taxable values, exemptions and overlapping taxing entities change during the same period?
Limit: A tax rate is not a tax bill. Property values, exemptions and overlapping taxing entities affect what a household pays.
Evidence pack includes chart rows, PDF pages, source URL/hash, methodology, summaries and edition ID; it does not bundle the source PDF.
Embed this graphic
This edition remains unchanged, even after newer records arrive. Check revision notes before reuse. Embeds contain no analytics scripts or cookies. Hosting still receives ordinary web requests.
Responsive width; adjust the iframe height for your layout. The data table remains scrollable inside the frame.
Reporting brief, source and accessible table
Short factual summary
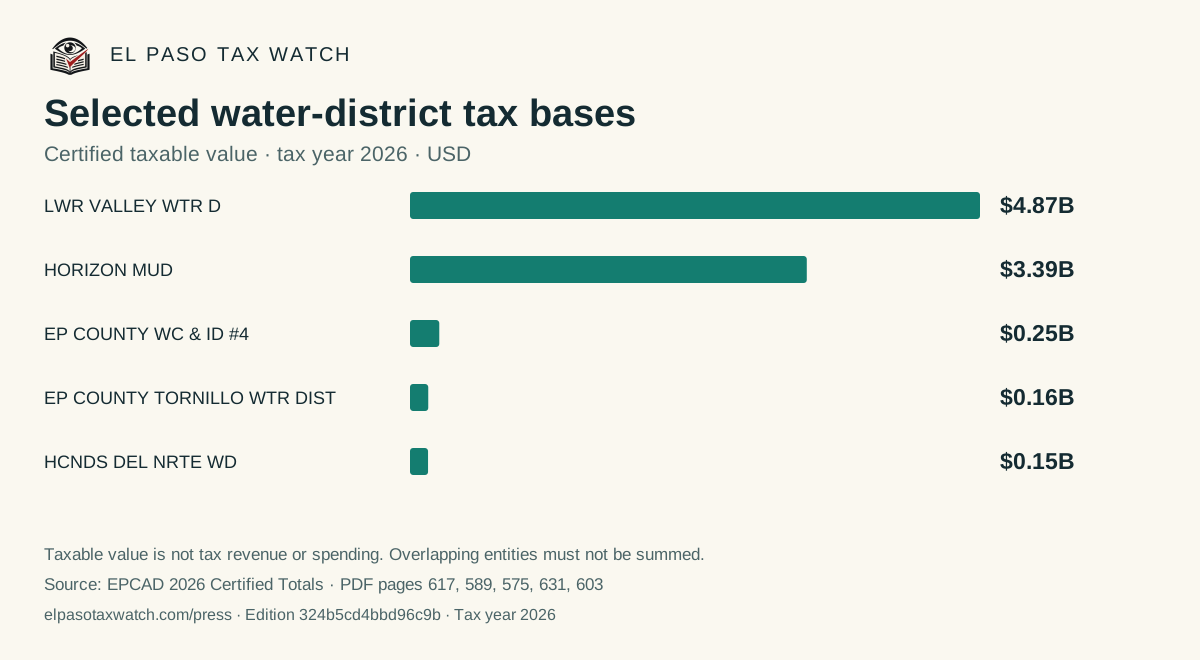
Selected water districts have separate certified taxable values. Their jurisdictions can overlap other taxing entities; these amounts must not be added to municipal or county values.
Resumen: Los distritos de agua seleccionados tienen bases gravables independientes. Sus jurisdicciones pueden superponerse con otras entidades; no se deben sumar estos valores a los municipales o del condado.
Question to pursue: Which parcels and services belong to each district? Verify district boundaries before making neighborhood comparisons.
Limit: Taxable value is not tax revenue or spending. Overlapping entities must not be summed.
Evidence pack includes chart rows, PDF pages, source URL/hash, methodology, summaries and edition ID; it does not bundle the source PDF.
Embed this graphic
This edition remains unchanged, even after newer records arrive. Check revision notes before reuse. Embeds contain no analytics scripts or cookies. Hosting still receives ordinary web requests.
Responsive width; adjust the iframe height for your layout. The data table remains scrollable inside the frame.
Reporting brief, source and accessible table
Short factual summary
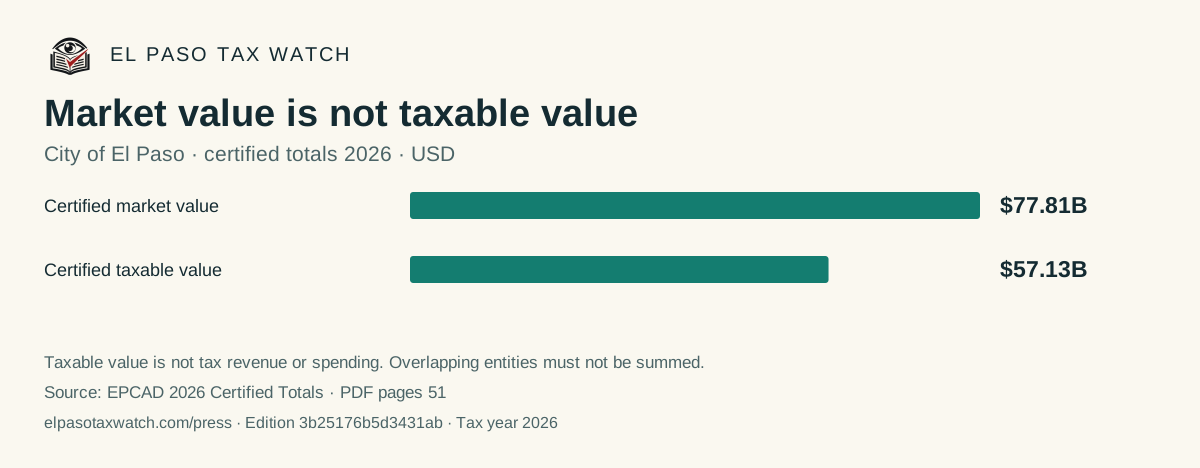
EPCAD reports $77.81B in certified market value and $57.13B in certified taxable value for the City of El Paso. The difference is not a measure of lost revenue or spending.
Resumen: El valor de mercado certificado y el valor gravable certificado son medidas distintas. La diferencia no equivale a ingresos perdidos ni a gasto público.
Question to pursue: What explains the difference? Consult exemption and valuation schedules before attributing it to any policy.
Limit: Taxable value is not tax revenue or spending. Overlapping entities must not be summed.
Evidence pack includes chart rows, PDF pages, source URL/hash, methodology, summaries and edition ID; it does not bundle the source PDF.
Embed this graphic
This edition remains unchanged, even after newer records arrive. Check revision notes before reuse. Embeds contain no analytics scripts or cookies. Hosting still receives ordinary web requests.
Responsive width; adjust the iframe height for your layout. The data table remains scrollable inside the frame.
Reporting brief, source and accessible table
Short factual summary
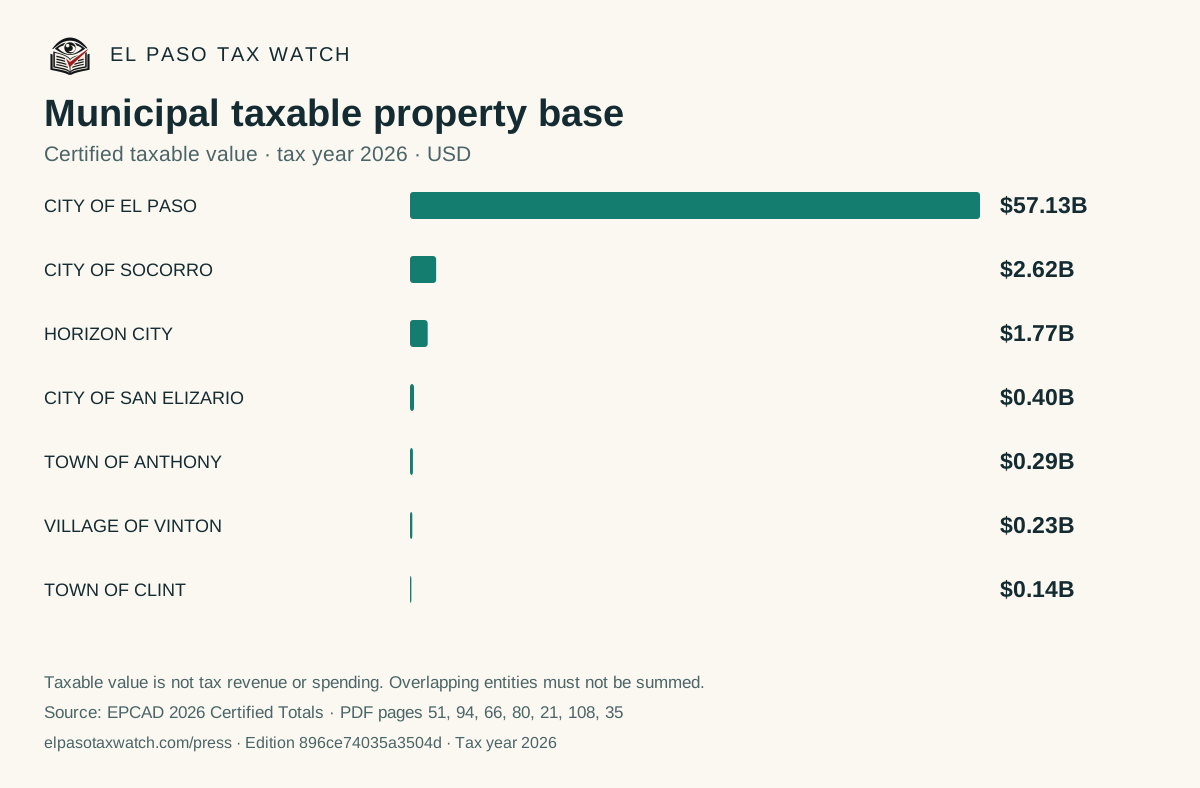
Certified taxable property values differ widely across El Paso County municipalities. These figures describe the tax base, not taxes collected, budgets, or household bills.
Resumen: Los valores catastrales gravables certificados varían entre los municipios. Representan la base gravable, no la recaudación, los presupuestos ni las facturas de los hogares.
Question to pursue: How do exemptions, valuation changes and adopted rates affect each municipality’s revenue? These totals alone cannot answer that question.
Limit: Taxable value is not tax revenue or spending. Overlapping entities must not be summed.
This is a publication log, not a feed of newly enacted government decisions. Frozen editions are preserved. A new edition can reflect changed data or presentation; compare its evidence pack before reporting a change.
Published budgets, presentations, tax orders and calculation worksheets. A budget is not a payment register; distinguish fiscal year from tax year and proposed rates from adopted orders.
Budgets, service fees, audit and board documents. The finance page lists FY25 budget and FY23 audit, but the September 2026 meeting archive links an FY27 approved budget. Check both indexes and document dates; no actual payment totals are inferred.
Financial statements, annual reports, financial plans and contribution allocations alongside service studies. Preserve the named reporting entity and fiscal year; upload dates are not reporting periods. Plans, partner contributions and audited expenses must not be summed as separate spending.
Official audited-financial-report and purchasing entry points, including document links in the public menu script. Dynamic board and purchasing records still require separate review; an award is not a payment and an accessible shell does not establish current coverage.
The lookup desk now routes individual addresses to the official combined bill and exposes verified capital-related County checks. Named-project payment totals remain unavailable when the register omits a project ID; those rows are marked unassigned rather than matched by guesswork. The City rate history does not estimate a household bill, and the General Fund comparison does not represent all City spending.
Follow the evidence
RSS for new graphic editions is automatic on publication. Email alerts below remain manually curated and topic-based; entity-specific delivery is not yet available.
Get sourced alerts
Receive occasional, manually curated email alerts when verified El Paso tax, budget, contract, meeting, or records information changes.
Your email is stored privately and used only for the topics selected.